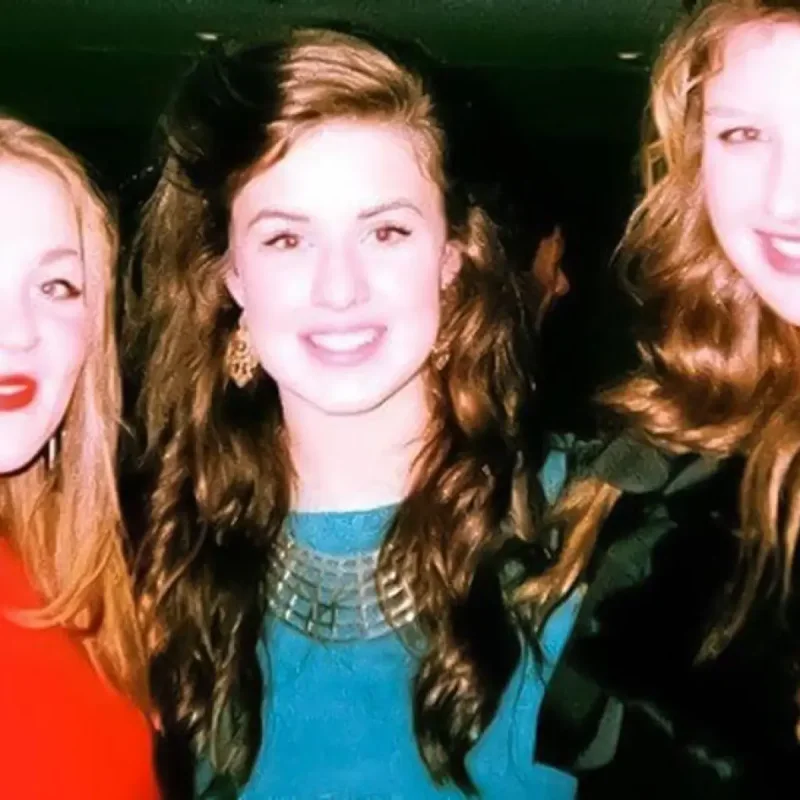
Three friends who attended the University of Newcastle have experienced sharply different financial outcomes from Britain's Plan 2 student loan system.
Lizzy, Libby, and Charlotte began university in 2012, borrowed about £37,500 each for tuition and living costs, and now face contrasting balances and repayment prospects shaped by their earnings and financial circumstances.
Their experiences come as the UK government faces pressure to make student financing fairer.
According to the Institute for Fiscal Studies, research published in February suggests graduates with a £50,000 Plan 2 balance generally need to earn about £63,000 or more for their debt to begin decreasing.
Under changes announced by the government in November, the income threshold for repayments is set to remain frozen for three years.
The change means graduates would begin repaying sooner and make larger monthly payments.
Plan 2 loans were introduced in England in 2012 and remain available in Wales, with outstanding balances written off after 30 years.
Contrasting Earnings and Balances
Charlotte, a physiotherapist in Bristol, earns about £50,000 after working for the NHS and later moving into the private sector.
She also completed a master's degree after university, but interest continues to outpace her repayments.
"Since April this year, I've paid off in the region of £450 and I've accrued over £500 in interest," Charlotte said.
Her experience has left her frustrated with a balance that continues to grow despite regular payments.
"It makes me angry... it's just disheartening," Charlotte said.
Libby, a project manager at a housing association who lives in Worcester, earns £72,000.
Despite earning above the national average of £39,039, she said her outstanding student loan has remained around £47,000 for several years.
Her maternity leave is reducing her earnings and monthly repayments, while interest continues to accumulate.
"I just had no concept that the debt was going to go up," Libby said, recalling that she cried when her first student loan statement arrived after graduation.
She expects the balance to remain a long-term burden until the loan is eventually written off.
"It feels like I will never pay it off, so it's something that I'm kind of just sucking up until the loan is written off," Libby said.
Libby also compared her situation with that of her partner, who took the same course but began university a year earlier, before the introduction of Plan 2 and the near-tripling of tuition fees.
She said the difference leaves her paying thousands of pounds more each year toward student debt.
Lizzy, who studied economics and now works in financial services, earns £85,000 and lives in Bristol.
She chose to clear her student loan early using money borrowed from her family, after estimating that her earnings trajectory would otherwise leave her repaying the debt for 11 years.
She hopes to repay her family within four years and estimates the decision will save her about £20,000 in interest.
Lizzy said her decision reflected both her financial position and her expectations for future earnings.
"I made a gamble on my future self to actually repay it," Lizzy said.
She acknowledged that paying off the debt early is not a realistic option for everyone, particularly graduates who cannot afford a substantial upfront payment.
"I'm in a very privileged position to be able to do that...
Buying your way out of the system or not being in at all is in itself a luxury.
It buys you freedom," Lizzy said.
Expert Caution and Timing Effects
Financial experts have cautioned graduates against making voluntary repayments without assessing their circumstances.
MoneySavingExpert.
com founder Martin Lewis has warned that early repayment may benefit only higher earners and that most borrowers should not be pressured into paying more than required.
Finance journalist Holly Mead told the BBC that large voluntary repayments could make sense for graduates confident they will clear their balances.
Smaller additional payments, however, may offer little benefit and could mean borrowers pay more than necessary.
Lizzy and Libby completed their A-levels in 2011 but delayed university entry by a year.
Libby took a gap year, while Lizzy resat economics after missing her expected grade by one mark.
Lizzy said she understood that the delay would mean higher tuition fees but did not realize how significantly the repayment terms would differ.
"I think that's something that took me probably the best part of 10 years to understand," Lizzy said.
Her twin sister began university in 2011 and accumulated less debt, highlighting how the timing of university entry affected the amount graduates borrowed and the terms governing repayment.
Campaigners are awaiting potential changes to the system in the government's October Budget.